 DALI#
This section shows how to construct Derivative Approximation for
LIkelihoods (DALI) tensors using derivkit.forecast_kit.ForecastKit,
and how to sample and visualize the resulting non-Gaussian posterior.
The DALI expansion extends the Fisher matrix by including higher-order
derivative information, allowing non-Gaussian structure in the likelihood
to be approximated locally around a fiducial parameter point theta0.
In DerivKit, DALI tensors are returned using an introduced-at-order convention: each forecast order contributes a tuple of tensors, and all orders up to the requested one are returned.
The model must map parameters theta to a 1D data vector, and the observable
covariance matrix must have shape (n, n), where n is the length of the
data vector.
For a conceptual overview of DALI forecasting and its interpretation, see ForecastKit.
Basic usage#
DALI tensor shapes#
For p model parameters, the DALI expansion returns tensors with the
following shapes:
order 1 (Fisher; “singlet-DALI”):
Fwith shape(p, p)
order 2 (doublet-DALI):
D1with shape(p, p, p)D2with shape(p, p, p, p)
order 3 (triplet-DALI):
T1with shape(p, p, p, p)T2with shape(p, p, p, p, p)T3with shape(p, p, p, p, p, p)
All tensors are evaluated at the fiducial parameter point theta0.
The forecast order specifies the highest derivative order of the forward model included in the DALI expansion, rather than the polynomial degree of the resulting log-likelihood. For example, doublet-DALI includes terms up to fourth order in parameter displacements.
The example below constructs DALI tensors around a fiducial parameter
point theta0 using a simple toy model.
>>> import numpy as np
>>> from derivkit import ForecastKit
>>> np.set_printoptions(precision=8, suppress=True)
>>> # Define a nonlinear toy model: R^2 -> R^3
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a**2 + 2.0 * b], dtype=float)
>>> # Fiducial parameters and covariance
>>> theta0 = np.array([1.0, 2.0])
>>> cov = np.eye(3)
>>> # Build ForecastKit and compute DALI tensors up to second order
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> dali = fk.dali(forecast_order=2)
>>> F = dali[1][0]
>>> D1, D2 = dali[2]
>>> print(F.shape)
(2, 2)
>>> print(D1.shape)
(2, 2, 2)
>>> print(D2.shape)
(2, 2, 2, 2)
Choosing a derivative backend#
As with Fisher forecasting, you can control how derivatives are computed by
passing method and backend-specific options.
All keyword arguments are forwarded to
derivkit.derivative_kit.DerivativeKit.differentiate().
>>> import numpy as np
>>> from derivkit import ForecastKit
>>> np.set_printoptions(precision=8, suppress=True)
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a**2 + 2.0 * b], dtype=float)
>>> theta0 = np.array([1.0, 2.0])
>>> cov = np.eye(3)
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> dali = fk.dali(
...     forecast_order=2,
...     method="finite",
...     n_workers=2,
...     stepsize=1e-2,
...     num_points=5,
...     extrapolation="ridders",
...     levels=4,
... )
>>> D1, D2 = dali[2]
>>> print(D1.shape)
(2, 2, 2)
>>> print(D2.shape)
(2, 2, 2, 2)
Parallel execution#
DALI tensor components can be computed in parallel using n_workers.
This parallelizes derivative evaluations across parameters and tensor entries.
>>> import numpy as np
>>> from derivkit import ForecastKit
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a**2 + 2.0 * b], dtype=float)
>>> fk = ForecastKit(
...     function=model,
...     theta0=np.array([1.0, 2.0]),
...     cov=np.eye(3),
... )
>>> dali = fk.dali(forecast_order=2, n_workers=4)
>>> D1, D2 = dali[2]
>>> print(D1.shape)
(2, 2, 2)
>>> print(D2.shape)
(2, 2, 2, 2)
Sampling and visualization#
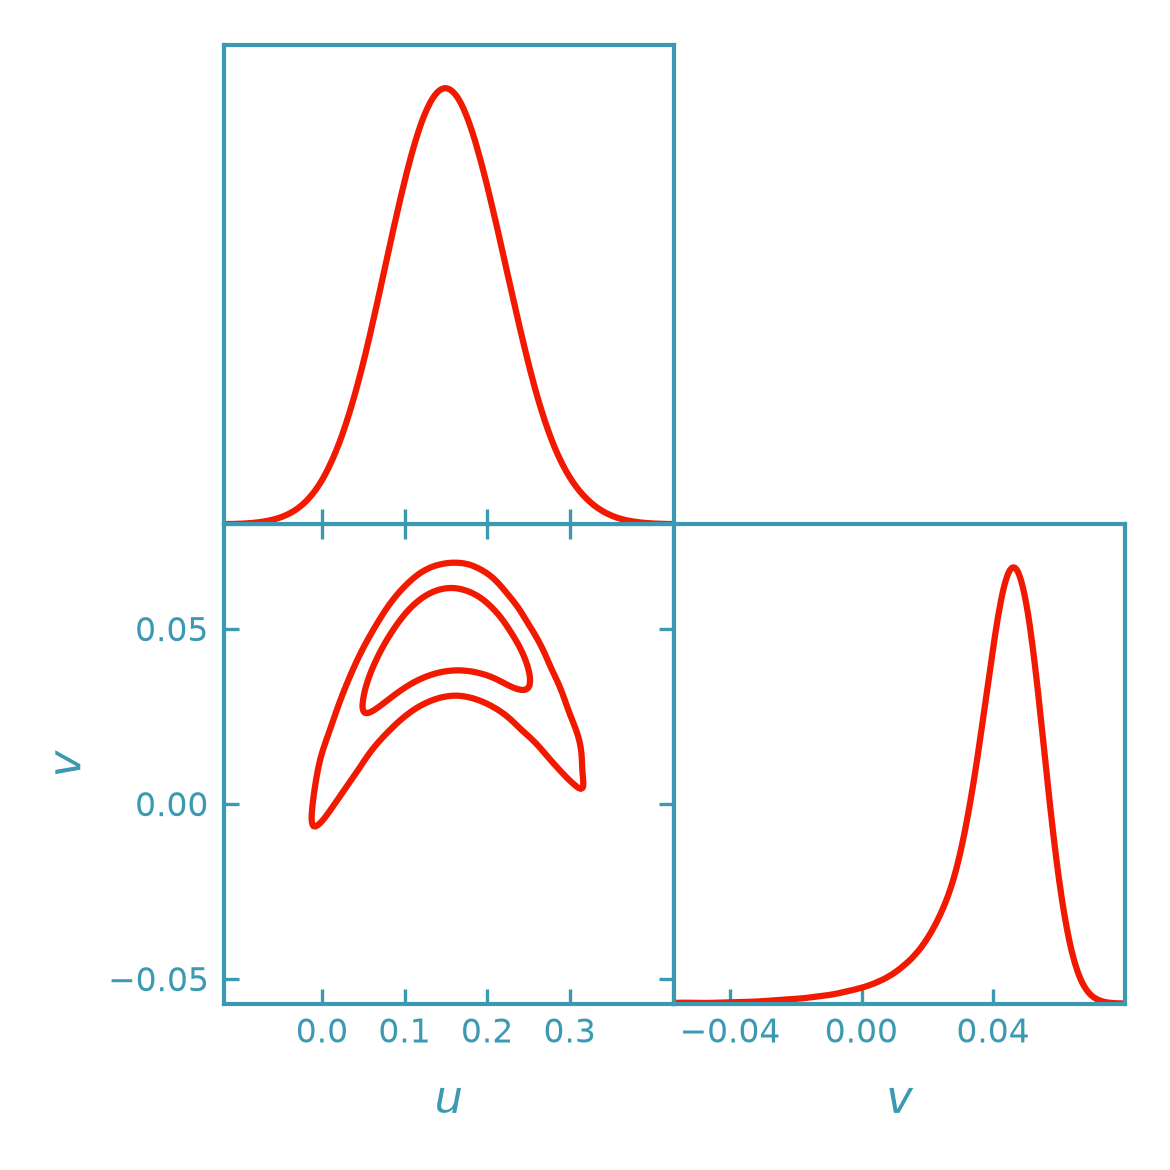
Once the DALI tensors have been constructed, DerivKit can generate GetDist
samples from the DALI-expanded posterior using either emcee or importance
sampling with a Fisher–Gaussian proposal. Both return a
getdist.MCSamples object. The resulting contours describe the
DALI approximation, not the exact nonlinear posterior.
Sampling the DALI posterior with emcee#
This example uses a two-parameter nonlinear benchmark with a curved
parameter degeneracy. The DALI expansion captures departures from the
locally Gaussian Fisher approximation, and emcee samples the resulting
DALI-expanded posterior.
>>> import numpy as np
>>> from getdist import plots as getdist_plots
>>> from derivkit import ForecastKit
>>> def model(theta):
...     u, v = theta
...     du, dv = u - 0.15, v - 0.05
...     return np.array([
...         1.0 + 1.4 * du + 0.15 * dv + 0.20 * du**2 + 0.06 * du * dv,
...         0.8 + 10.0 * (dv + 1.8 * du**2 - 0.3 * du**3 + 0.20 * du * dv),
...     ])
>>> theta0 = np.array([0.15, 0.05])
>>> sigma = 0.10 * np.abs(model(theta0))
>>> cov = np.outer(sigma, sigma) * np.array([[1.0, 0.3], [0.3, 1.0]])
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> dali = fk.dali(forecast_order=2)
>>> samples = fk.getdist_dali_emcee(
...     dali=dali,
...     names=["u", "v"],
...     labels=[r"u", r"v"],
...     label="DALI (emcee)",
... )
>>> dk_red = "#f21901"
>>> line_width = 1.5
>>> plotter = getdist_plots.get_subplot_plotter(width_inch=3.9)
>>> plotter.settings.linewidth_contour = line_width
>>> plotter.settings.linewidth = line_width
>>> plotter.settings.figure_legend_frame = False
>>> plotter.settings.legend_rect_border = False
>>> plotter.triangle_plot(
...     [samples],
...     params=["u", "v"],
...     filled=False,
...     contour_colors=[dk_red],
...     contour_lws=[line_width],
...     contour_ls=["-"],
... )
>>> samples.numrows > 0
True
(png)
Sampling the DALI posterior with importance sampling#
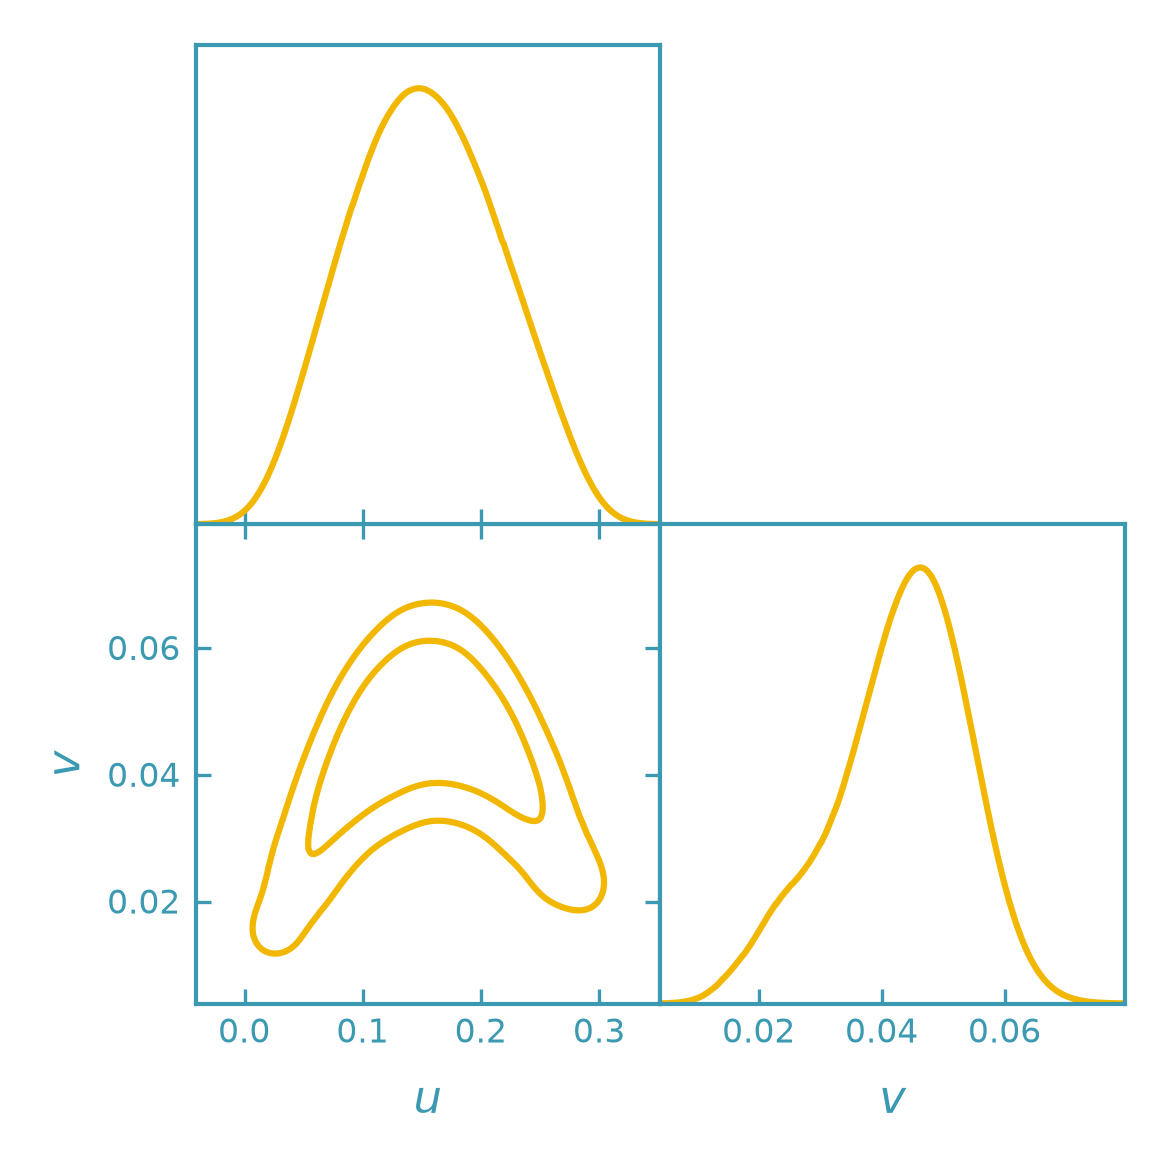
Using the same nonlinear benchmark as the previous example, we now sample the DALI posterior through importance weighting of a Fisher–Gaussian proposal rather than running an MCMC chain.
This provides a faster alternative to emcee when the Fisher–Gaussian
proposal adequately covers the DALI posterior.
>>> import numpy as np
>>> from getdist import plots as getdist_plots
>>> from derivkit import ForecastKit
>>> def model(theta):
...     u, v = theta
...     du, dv = u - 0.15, v - 0.05
...     return np.array([
...         1.0 + 1.4 * du + 0.15 * dv + 0.20 * du**2 + 0.06 * du * dv,
...         0.8 + 10.0 * (dv + 1.8 * du**2 - 0.3 * du**3 + 0.20 * du * dv),
...     ])
>>> theta0 = np.array([0.15, 0.05])
>>> sigma = 0.10 * np.abs(model(theta0))
>>> cov = np.outer(sigma, sigma) * np.array([[1.0, 0.3], [0.3, 1.0]])
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> dali = fk.dali(forecast_order=2)
>>> samples = fk.getdist_dali_importance(
...     dali=dali,
...     names=["u", "v"],
...     labels=[r"u", r"v"],
...     label="DALI (importance)",
...     n_samples=50_000,
...     seed=0,
...     kernel_scale=1.3,
... )
>>> dk_yellow = "#f2b701"
>>> line_width = 1.5
>>> plotter = getdist_plots.get_subplot_plotter(width_inch=3.9)
>>> plotter.settings.linewidth_contour = line_width
>>> plotter.settings.linewidth = line_width
>>> plotter.settings.figure_legend_frame = False
>>> plotter.settings.legend_rect_border = False
>>> plotter.triangle_plot(
...     [samples],
...     params=["u", "v"],
...     filled=False,
...     contour_colors=[dk_yellow],
...     contour_lws=[line_width],
...     contour_ls=["-"],
... )
>>> samples.numrows > 0
True
(png)
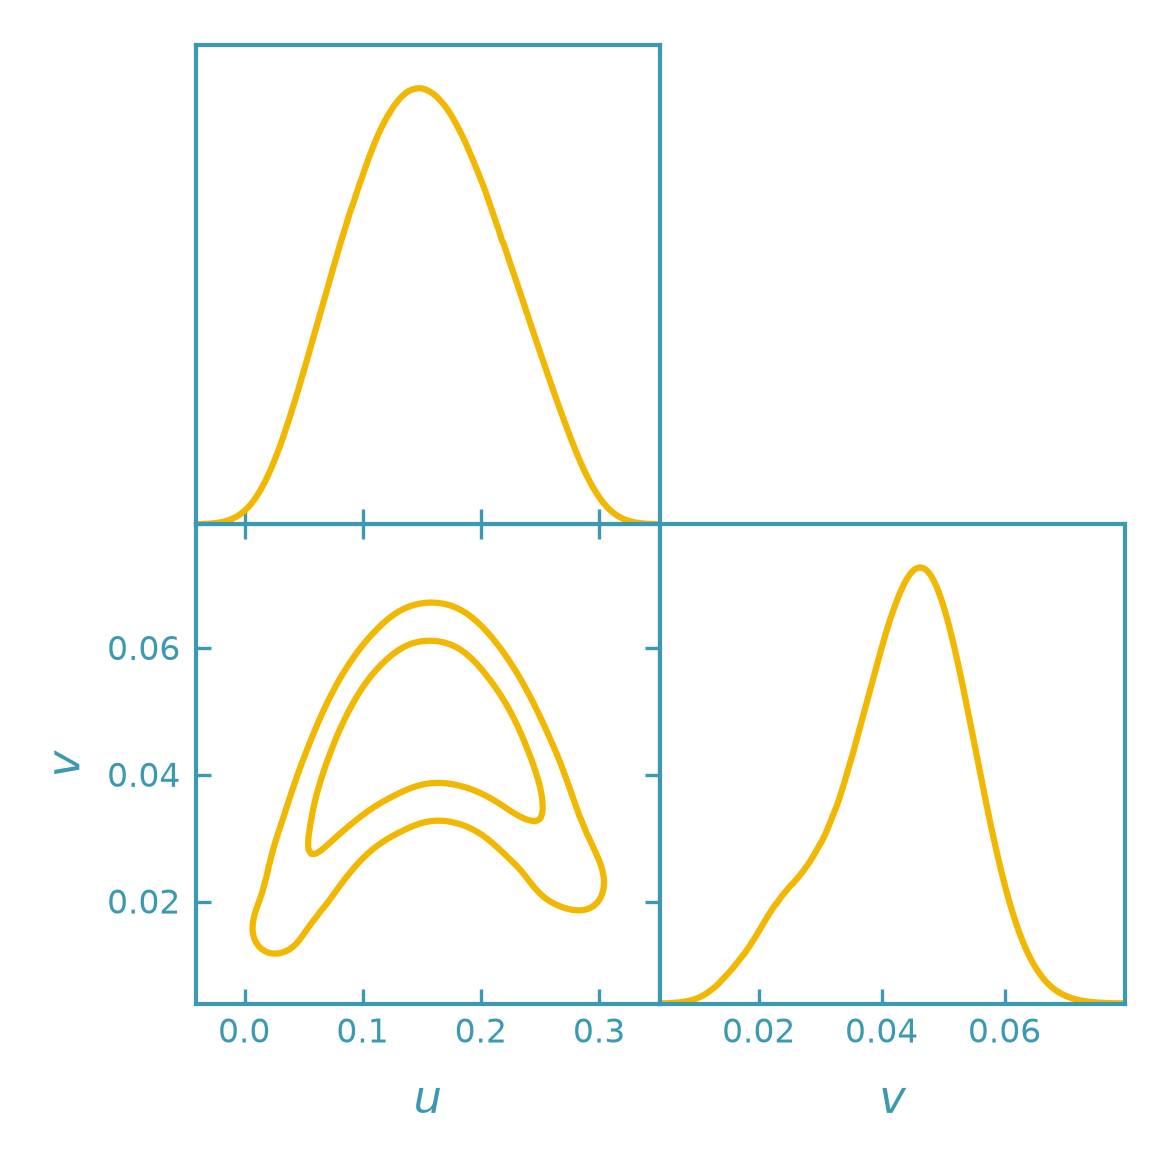
Note
This example illustrates the importance-sampling API rather than
validating its accuracy for this particular posterior. For scientific
applications, check the effective sample size and compare against
an independent sampler such as emcee, especially for strongly
non-Gaussian posteriors.
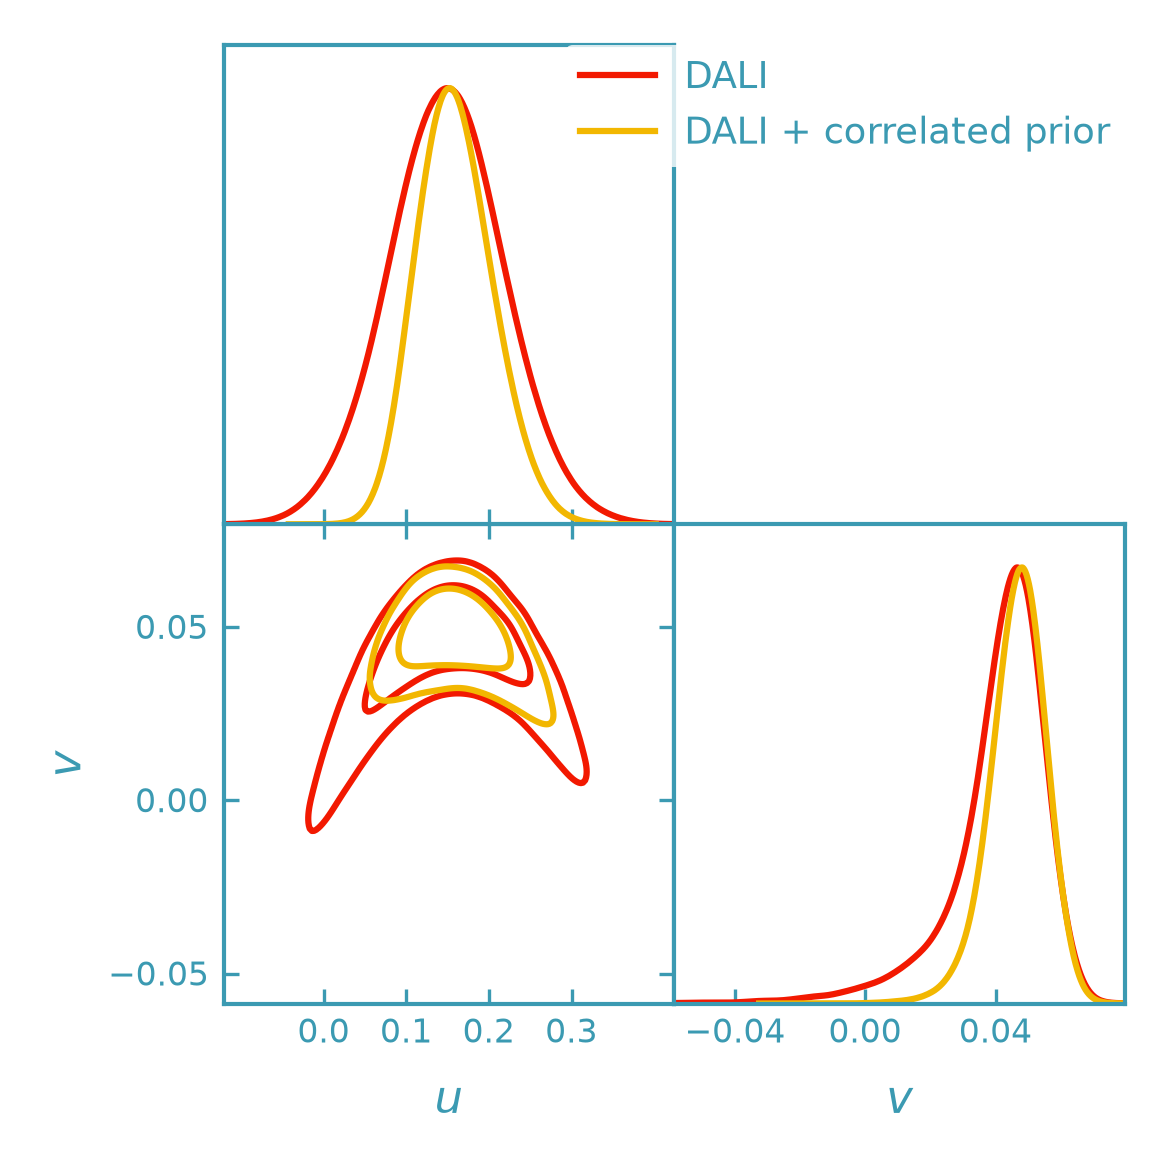
Including priors in DALI contours#
Priors can be included in DALI sampling through prior_terms and
prior_bounds. Here, we use the same nonlinear benchmark as above
to compare the DALI posterior with and without a correlated Gaussian prior.
An informative prior can modify the orientation and extent of the posterior contours. If sufficiently restrictive, it can also suppress the non-Gaussian structure captured by DALI.
>>> import numpy as np
>>> from getdist import plots as getdist_plots
>>> from derivkit import ForecastKit
>>> def model(theta):
...     u, v = theta
...     du, dv = u - 0.15, v - 0.05
...     return np.array([
...         1.0 + 1.4 * du + 0.15 * dv + 0.20 * du**2 + 0.06 * du * dv,
...         0.8 + 10.0 * (dv + 1.8 * du**2 - 0.3 * du**3 + 0.20 * du * dv),
...     ])
>>> theta0 = np.array([0.15, 0.05])
>>> sigma = 0.10 * np.abs(model(theta0))
>>> cov = np.outer(sigma, sigma) * np.array([[1.0, 0.3], [0.3, 1.0]])
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> dali = fk.dali(forecast_order=2)
>>> samples_base = fk.getdist_dali_emcee(
...     dali=dali,
...     names=["u", "v"],
...     labels=[r"u", r"v"],
...     label="DALI",
... )
>>> prior_bounds = [(-2.0, 2.0), (-2.0, 2.0)]
>>> su, sv, rho = 0.08, 0.03, -0.6
>>> cov_prior = np.array([
...     [su**2, rho * su * sv],
...     [rho * su * sv, sv**2],
... ])
>>> prior_terms = [("gaussian", {"mean": theta0, "cov": cov_prior})]
>>> samples_prior = fk.getdist_dali_emcee(
...     dali=dali,
...     names=["u", "v"],
...     labels=[r"u", r"v"],
...     label="DALI + correlated prior",
...     prior_bounds=prior_bounds,
...     prior_terms=prior_terms,
... )
>>> dk_red = "#f21901"
>>> dk_yellow = "#f2b701"
>>> line_width = 1.5
>>> plotter = getdist_plots.get_subplot_plotter(width_inch=3.9)
>>> plotter.settings.linewidth_contour = line_width
>>> plotter.settings.linewidth = line_width
>>> plotter.settings.figure_legend_frame = False
>>> plotter.settings.legend_rect_border = False
>>> plotter.triangle_plot(
...     [samples_base, samples_prior],
...     params=["u", "v"],
...     filled=[False, False],
...     contour_colors=[dk_red, dk_yellow],
...     contour_lws=[line_width, line_width],
...     contour_ls=["-", "-"],
... )
>>> (samples_base.numrows > 0) and (samples_prior.numrows > 0)
True
(png)
Notes and conventions#
The non-Gaussianity here comes from the nonlinear forward model.
getdist.MCSamples.loglikesstores minus the log-posterior (up to an additive constant), following GetDist conventions.Importance sampling uses a Fisher–Gaussian proposal;
kernel_scalecontrols its width. If weights become extremely uneven, try increasing the scale slightly.Importance sampling is intended for fast visualization and exploratory work, and is reliable when the Fisher–Gaussian proposal closely matches the DALI posterior.
For science analyses requiring a robust exploration of the posterior, including non-Gaussian structure and tails, we recommend using emcee to sample the DALI-expanded posterior.
Typical workflow#
Compute DALI tensors with
ForecastKit(e.g.dali = fk.dali(forecast_order=2)).Use importance sampling for fast visualization and iteration.
Switch to
emceewhen robustness is required or strong non-Gaussianity leads to unstable importance weights.Visualize and compare results using GetDist triangle plots.
See also#
derivkit.forecast_kit.ForecastKitderivkit.forecast_kit.ForecastKit.dali()derivkit.forecast_kit.ForecastKit.logposterior_dali()derivkit.forecast_kit.ForecastKit.getdist_dali_emcee()derivkit.forecast_kit.ForecastKit.getdist_dali_importance()