 Fisher matrix#
This section shows how to construct a Fisher information matrix using
derivkit.forecast_kit.ForecastKit, and how to visualize Fisher
forecasts using GetDist.
The Fisher matrix characterizes the local curvature of the log-likelihood with respect to the model parameters. For a Gaussian likelihood with parameter-independent covariance, it is constructed from the first derivatives of the model predictions.
In DerivKit, the Fisher matrix is built from:
a model function mapping parameters
thetato a 1D data vectora fixed observable covariance matrix
cov
The primary interface for Fisher forecasting is
derivkit.forecast_kit.ForecastKit.fisher().
For a conceptual overview of Fisher forecasting, its interpretation, and other forecasting frameworks in DerivKit see ForecastKit.
Basic usage#
The model must return a 1D array of length n for an input parameter vector
theta of length p. The covariance must have shape (n, n).
>>> import numpy as np
>>> from derivkit import ForecastKit
>>> np.set_printoptions(precision=8, suppress=True)
>>> # Define a simple toy model: R^2 -> R^3
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a + 2.0 * b], dtype=float)
>>> # Fiducial parameters and covariance
>>> theta0 = np.array([1.0, 2.0])
>>> cov = np.eye(3)
>>> # Build ForecastKit and compute Fisher matrix
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> fisher = fk.fisher()
>>> print(fisher)
[[2. 2.]
 [2. 5.]]
>>> print(fisher.shape)
(2, 2)
Interpreting the result#
For p parameters, the Fisher matrix has shape (p, p).
The Fisher matrix encodes the local curvature of the likelihood with respect to the parameters.
The inverse Fisher matrix approximates the parameter covariance near
theta0; its diagonal elements give the parameter variances, while off-diagonal elements give the covariances between parameters.
>>> import numpy as np
>>> from derivkit import ForecastKit
>>> # Same toy model as above
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a + 2.0 * b], dtype=float)
>>> theta0 = np.array([1.0, 2.0])
>>> cov = np.eye(3)
>>> # Compute Fisher matrix and invert it
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> fisher = fk.fisher()
>>> cov_theta = np.linalg.inv(fisher)
>>> print(cov_theta.shape)
(2, 2)
>>> print(np.all(np.isfinite(cov_theta)))
True
Choosing a derivative backend#
The Fisher matrix is constructed from derivatives of the model with respect to
the parameters. You can control how these derivatives are computed by passing
method and backend-specific options.
All keyword arguments are forwarded to
derivkit.derivative_kit.DerivativeKit.differentiate().
>>> import numpy as np
>>> from derivkit import ForecastKit
>>> np.set_printoptions(precision=8, suppress=True)
>>> # Define the model
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a + 2.0 * b], dtype=float)
>>> theta0 = np.array([1.0, 2.0])
>>> cov = np.eye(3)
>>> # Use a finite-difference derivative backend
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> fisher = fk.fisher(
...     method="finite",
...     n_workers=2,
...     stepsize=1e-2,
...     num_points=5,
...     extrapolation="ridders",
...     levels=4,
... )
>>> print(fisher)
[[2. 2.]
 [2. 5.]]
Parallel execution#
The derivative evaluations used to construct the Fisher matrix can be
parallelized using n_workers.
This becomes important in practical forecasting applications with many parameters and costly model evaluations.
>>> import numpy as np
>>> from derivkit import ForecastKit
>>> # Model definition
>>> def model(theta):
...     return np.array([theta[0], theta[1], theta[0] + 2.0 * theta[1]])
>>> # Enable parallel execution
>>> fk = ForecastKit(function=model, theta0=np.array([1.0, 2.0]), cov=np.eye(3))
>>> fisher = fk.fisher(n_workers=4)
>>> print(fisher.shape)
(2, 2)
Notes on Fisher construction#
The Fisher matrix assumes a Gaussian likelihood with fixed covariance.
Derivatives are evaluated at
theta0.The choice of derivative backend can affect numerical accuracy and cost.
For likelihoods with parameter-dependent covariance, see the generalized Fisher matrix utilities.
Sampling and visualization#
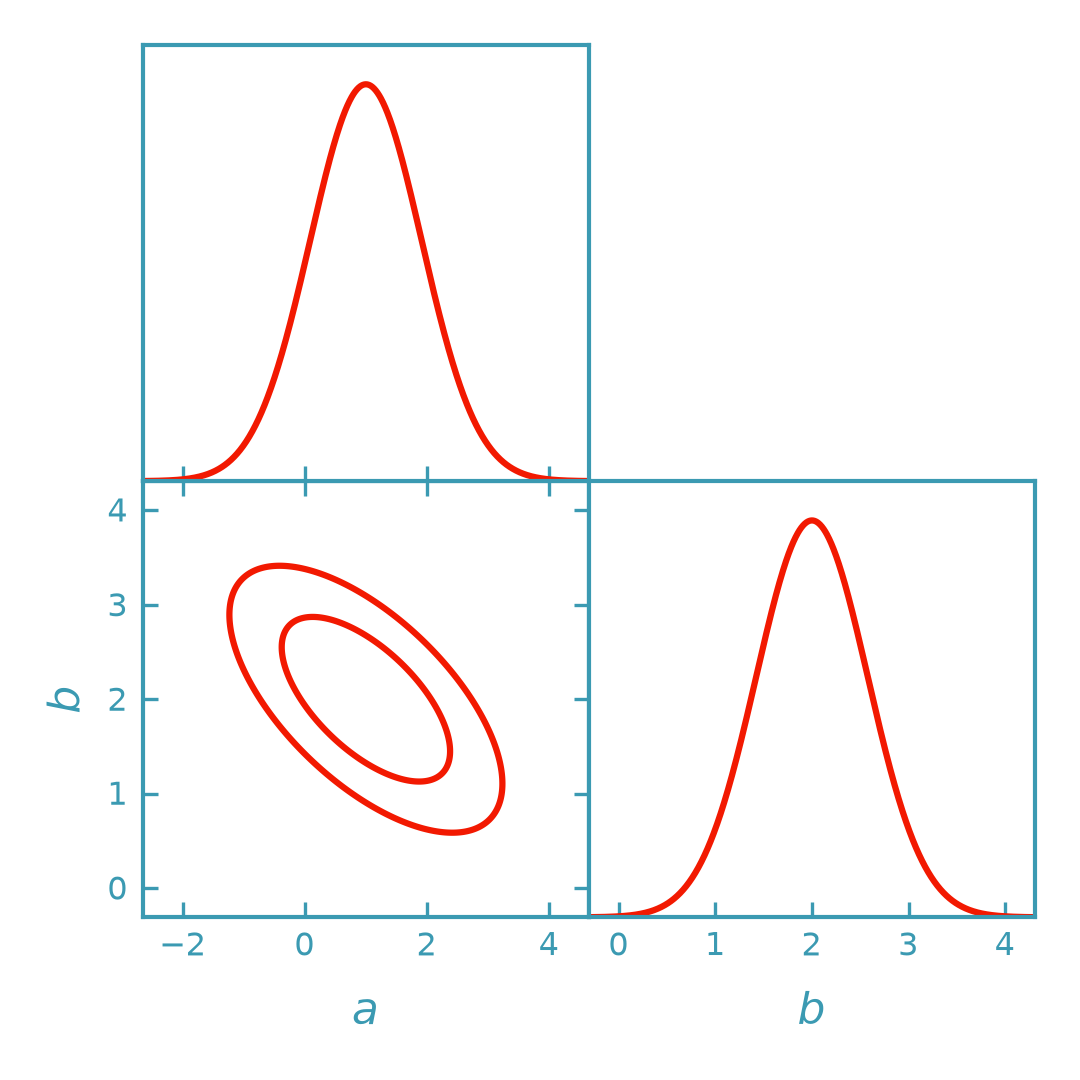
Once the Fisher matrix has been constructed, two complementary workflows
are available: passing an analytic Fisher Gaussian to GetDist, or explicitly
drawing samples and returning them as getdist.MCSamples.
Both can be visualized using GetDist triangle plots.
Analytic Gaussian#
Convert the Fisher matrix into an analytic Gaussian object compatible with GetDist. The Gaussian distribution is passed directly to GetDist for visualization, without explicitly drawing samples in DerivKit.
>>> import numpy as np
>>> from getdist import plots as getdist_plots
>>> from derivkit import ForecastKit
>>> # Define a simple toy model
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a + 2.0 * b], dtype=float)
>>> # Fiducial parameters and covariance
>>> theta0 = np.array([1.0, 2.0])
>>> cov = np.eye(3)
>>> # Compute Fisher matrix
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> fisher = fk.fisher(
...     method="finite",
...     stepsize=1e-2,
...     num_points=5,
...     extrapolation="ridders",
...     levels=4,
... )
>>> # Construct a Gaussian object for GetDist-managed sampling and visualization
>>> gnd = fk.getdist_fisher_gaussian(
...     fisher=fisher,
...     names=["a", "b"],
...     labels=[r"a", r"b"],
...     label="Fisher (Gaussian)",
... )
>>> # Plot Fisher ellipses in DerivKit red (rendered by the docs build)
>>> dk_red = "#f21901"
>>> line_width = 1.5
>>> plotter = getdist_plots.get_subplot_plotter(width_inch=3.6)
>>> plotter.settings.linewidth_contour = line_width
>>> plotter.settings.linewidth = line_width
>>> plotter.triangle_plot(
...     [gnd],
...     params=["a", "b"],
...     filled=[False],
...     contour_colors=[dk_red],
...     contour_lws=[line_width],
...     contour_ls=["-"],
... )
>>> isinstance(gnd, object)
True
(png)
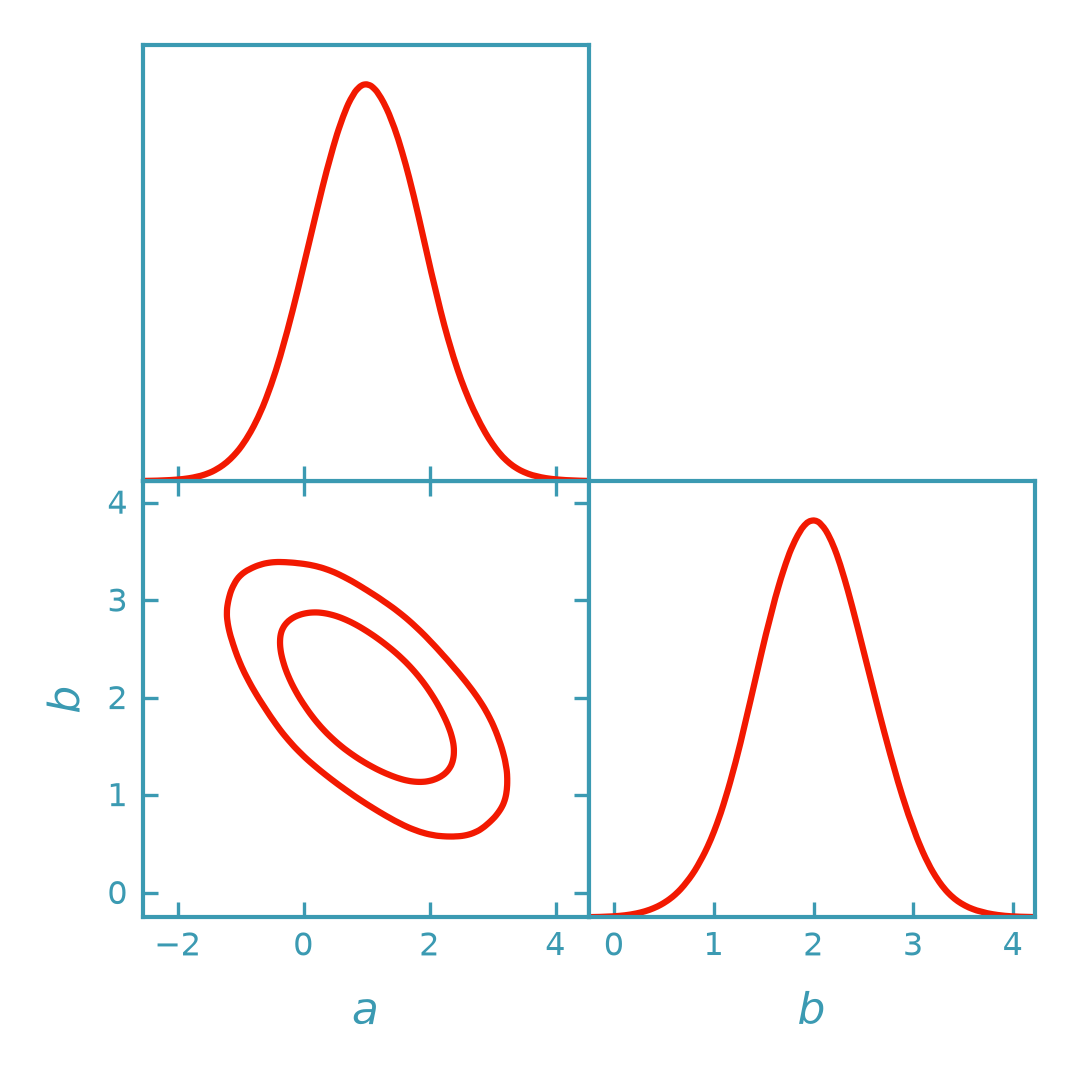
Sampling from the Fisher Gaussian#
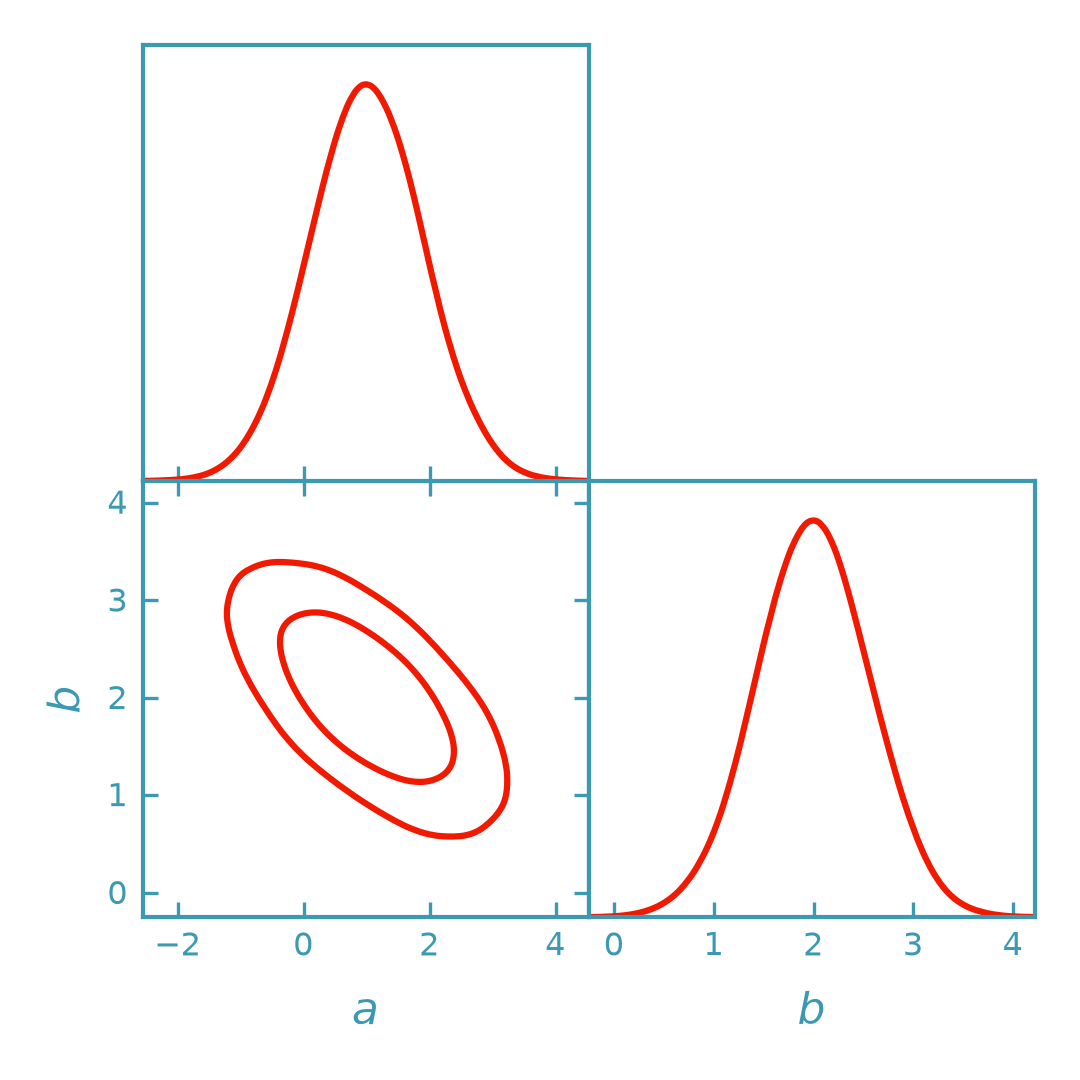
Alternatively, explicitly draw Monte Carlo samples from the Fisher Gaussian
and return them as a getdist.MCSamples object. This provides direct
access to the samples for further analysis, applying bounds, or combining
with other samples.
>>> import numpy as np
>>> from getdist import plots as getdist_plots
>>> from derivkit import ForecastKit
>>> # Define a simple toy model
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a + 2.0 * b], dtype=float)
>>> # Fiducial parameters and covariance
>>> theta0 = np.array([1.0, 2.0])
>>> cov = np.eye(3)
>>> # Compute Fisher matrix
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> fisher = fk.fisher(
...     method="finite",
...     stepsize=1e-2,
...     num_points=5,
...     extrapolation="ridders",
...     levels=4,
... )
>>> # Draw samples from the Fisher Gaussian
>>> samples = fk.getdist_fisher_samples(
...     fisher=fisher,
...     names=["a", "b"],
...     labels=[r"a", r"b"],
...     store_loglikes=True,
...     label="Fisher (samples)",
... )
>>> # Plot sample-based contours in DerivKit red (rendered by the docs build)
>>> dk_red = "#f21901"
>>> line_width = 1.5
>>> plotter = getdist_plots.get_subplot_plotter(width_inch=3.6)
>>> plotter.settings.linewidth_contour = line_width
>>> plotter.settings.linewidth = line_width
>>> plotter.triangle_plot(
...     [samples],
...     params=["a", "b"],
...     filled=False,
...     contour_colors=[dk_red],
...     contour_lws=[line_width],
...     contour_ls=["-"],
... )
>>> samples.numrows > 0
True
(png)
Including Gaussian priors in Fisher forecast#
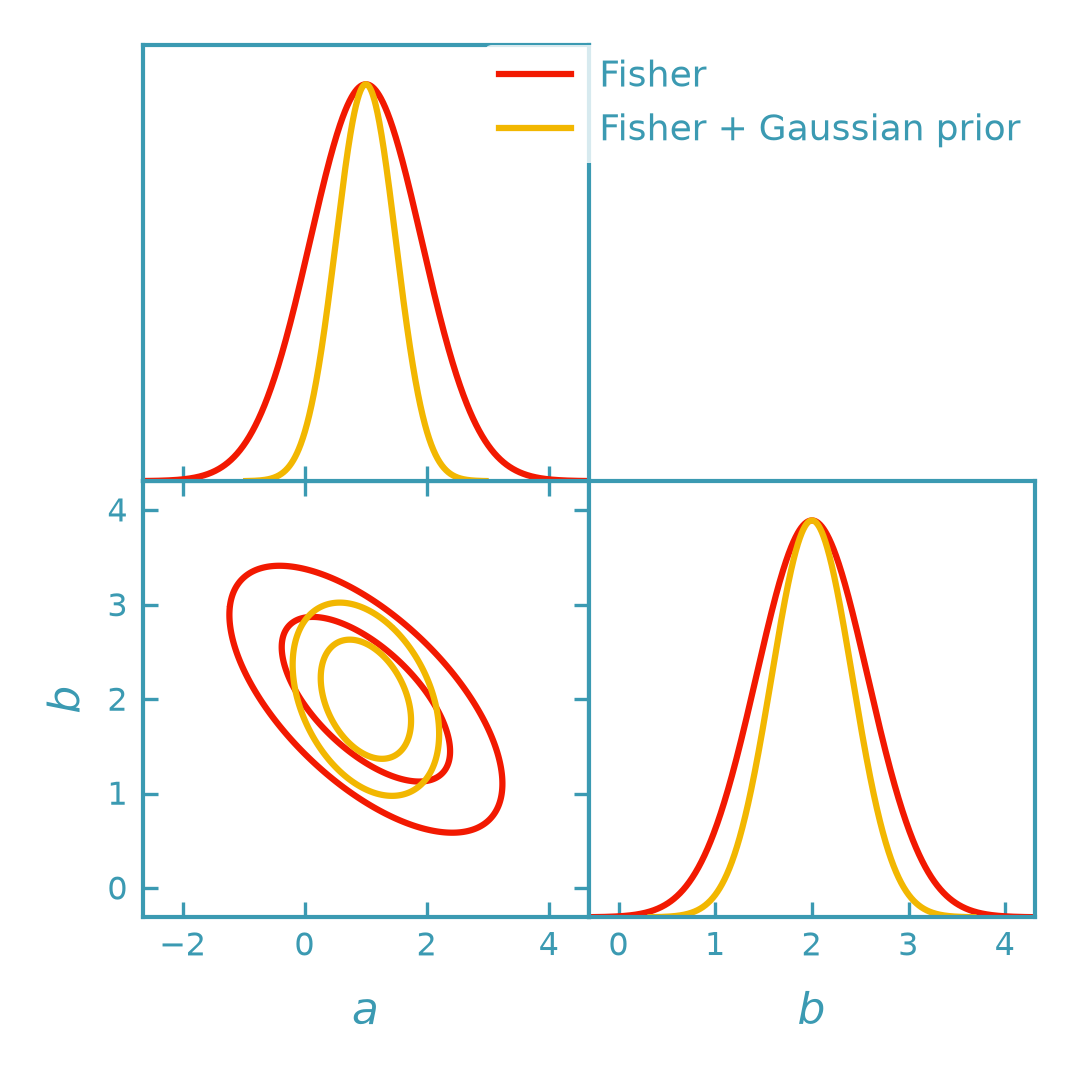
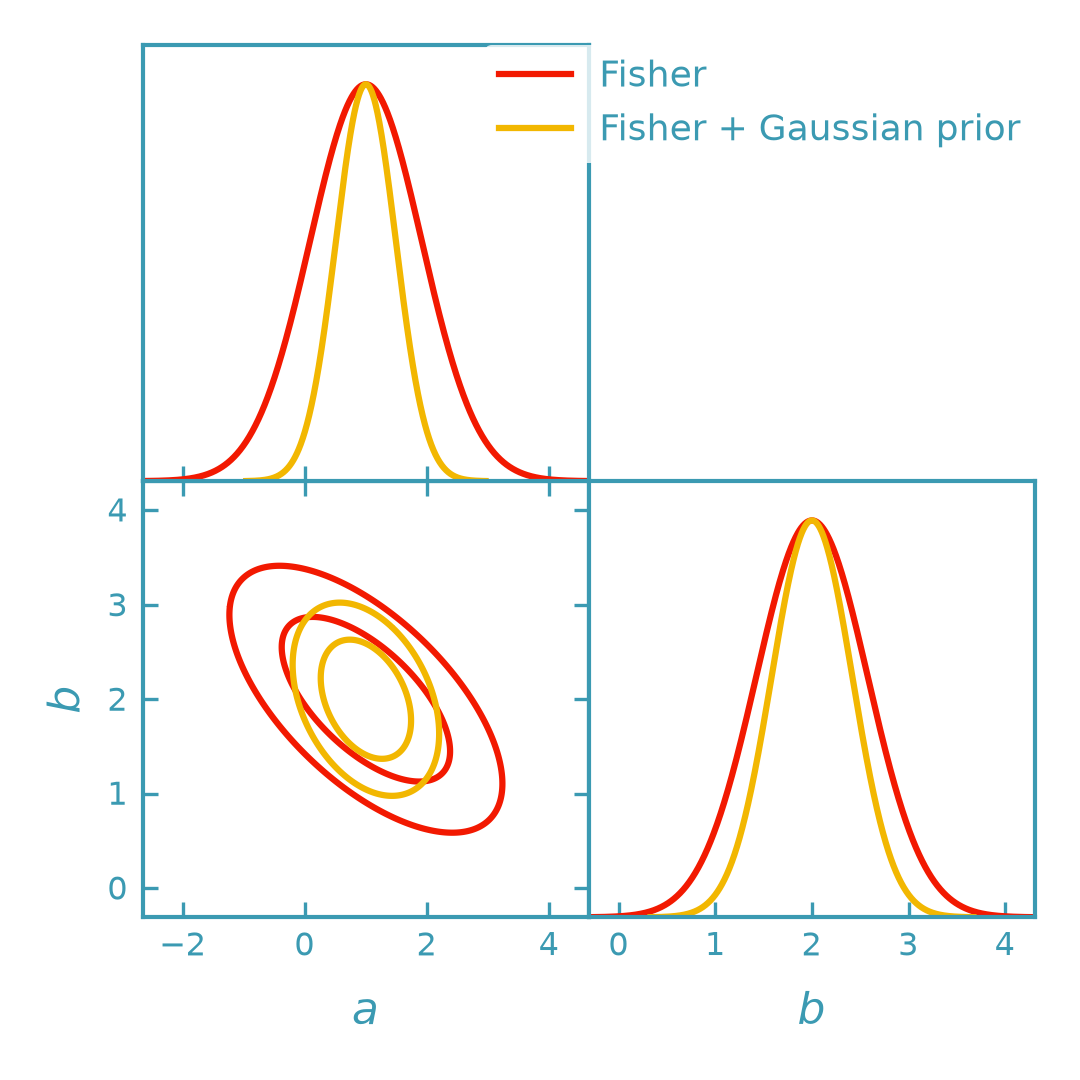
Gaussian priors can be included by adding their precision matrix (the inverse prior covariance) to the Fisher matrix before converting to GetDist objects. Below we overlay the original Fisher contours (red) with the Fisher+prior contours (yellow).
>>> import numpy as np
>>> from getdist import plots as getdist_plots
>>> from derivkit import ForecastKit
>>> np.set_printoptions(precision=8, suppress=True)
>>> # Same toy model as above
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a + 2.0 * b], dtype=float)
>>> theta0 = np.array([1.0, 2.0])
>>> cov = np.eye(3)
>>> # Fisher from the example above
>>> fk = ForecastKit(function=model, theta0=theta0, cov=cov)
>>> fisher_like = fk.fisher()
>>> # Gaussian prior: sigma_a = 0.6, sigma_b = 0.8 (diagonal prior covariance)
>>> sigma_prior = np.array([0.6, 0.8], dtype=float)
>>> fisher_prior = np.diag(1.0 / sigma_prior**2)
>>> fisher_post = fisher_like + fisher_prior
>>> # Convert both to analytic GetDist Gaussians
>>> g_like = fk.getdist_fisher_gaussian(
...     fisher=fisher_like,
...     names=["a", "b"],
...     labels=[r"a", r"b"],
...     label="Fisher",
... )
>>> g_post = fk.getdist_fisher_gaussian(
...     fisher=fisher_post,
...     names=["a", "b"],
...     labels=[r"a", r"b"],
...     label="Fisher + Gaussian prior",
... )
>>> # Overlay contours: red (likelihoods-only) and yellow (with prior)
>>> dk_red = "#f21901"
>>> dk_yellow = "#f2b701"
>>> line_width = 1.5
>>> plotter = getdist_plots.get_subplot_plotter(width_inch=3.6)
>>> plotter.settings.linewidth_contour = line_width
>>> plotter.settings.linewidth = line_width
>>> plotter.settings.figure_legend_frame = False
>>> plotter.settings.legend_rect_border = False
>>> plotter.triangle_plot(
...     [g_like, g_post],
...     params=["a", "b"],
...     filled=[False, False],
...     contour_colors=[dk_red, dk_yellow],
...     contour_lws=[line_width, line_width],
...     contour_ls=["-", "-"],
... )
>>> (g_like is not None) and (g_post is not None)
True
(png)
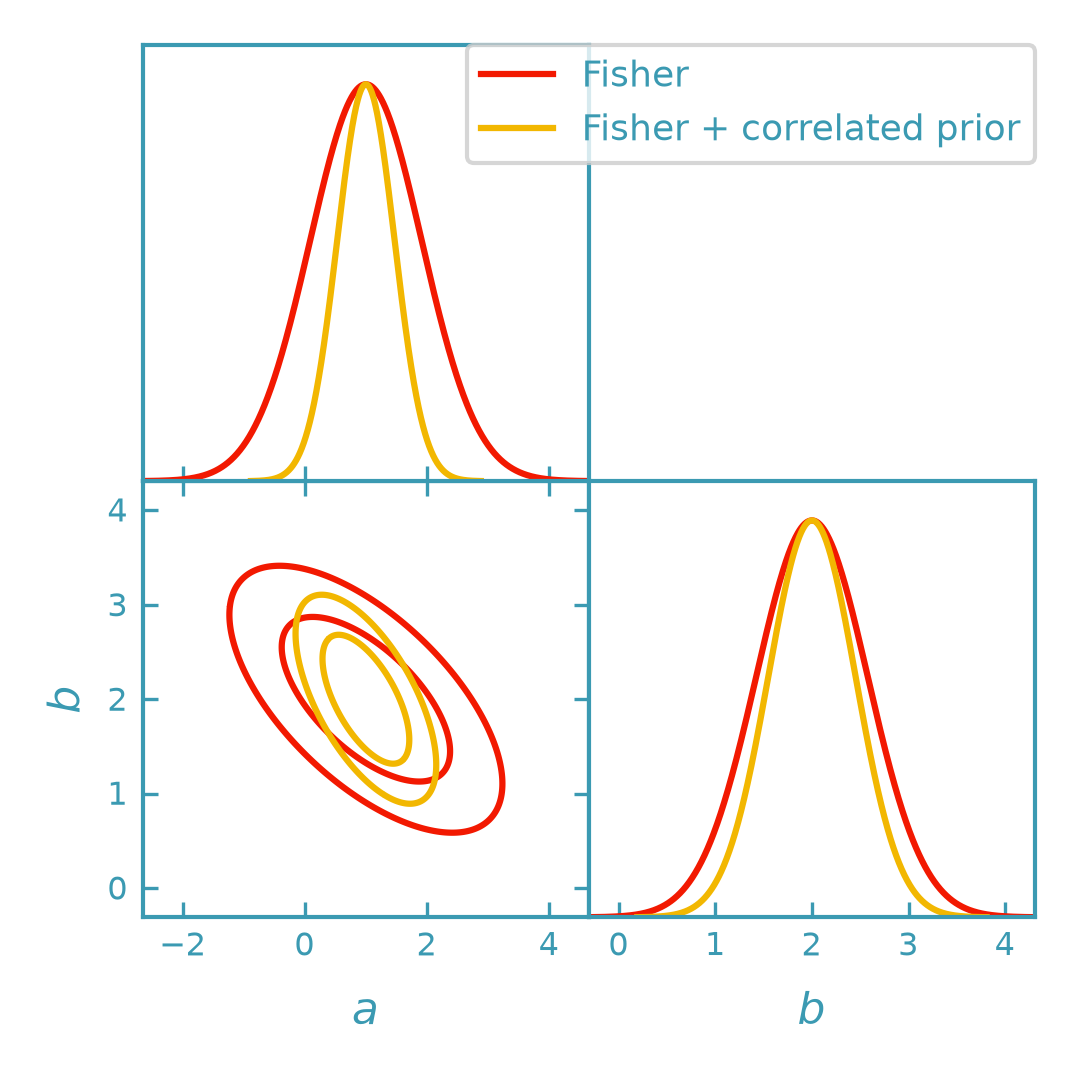
Including correlated Gaussian priors#
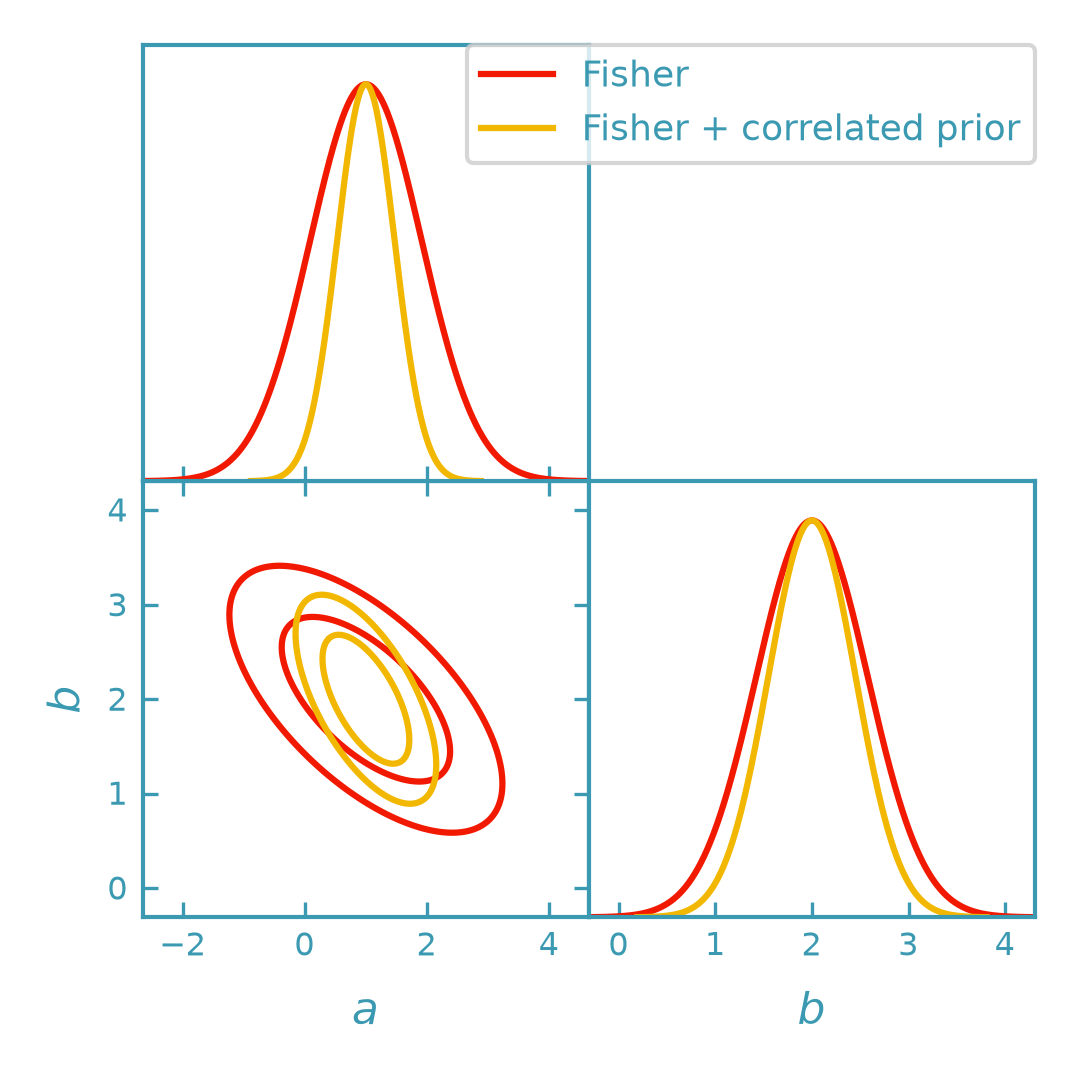
A correlated Gaussian prior can be included by adding its precision matrix to the Fisher matrix. Unlike a diagonal prior, a correlated prior contains off-diagonal covariance terms and can therefore change the orientation of the resulting confidence contours.
Below, the Fisher-only contours (red) are compared with those obtained after including a correlated Gaussian prior (yellow).
The derivkit.forecasting.priors_core.prior_gaussian() utility constructs the corresponding log-prior,
while its covariance is used directly to update the Fisher matrix.
The prior mean is set to the fiducial point theta0, so the
posterior Gaussian remains centered there.
>>> import numpy as np
>>> from getdist import plots as getdist_plots
>>> from derivkit import ForecastKit
>>> from derivkit.forecasting.priors_core import prior_gaussian
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a + 2.0 * b], dtype=float)
>>> theta0 = np.array([1.0, 2.0])
>>> fk = ForecastKit(function=model, theta0=theta0, cov=np.eye(3))
>>> fisher_like = fk.fisher()
>>> sigma_a, sigma_b, rho = 0.6, 0.8, -0.7
>>> cov_prior = np.array([
...     [sigma_a**2, rho * sigma_a * sigma_b],
...     [rho * sigma_a * sigma_b, sigma_b**2],
... ])
>>> logprior = prior_gaussian(mean=theta0, cov=cov_prior)
>>> fisher_post = fisher_like + np.linalg.inv(cov_prior)
>>> g_like = fk.getdist_fisher_gaussian(
...     fisher=fisher_like, names=["a", "b"], labels=[r"a", r"b"],
...     label="Fisher",
... )
>>> g_post = fk.getdist_fisher_gaussian(
...     fisher=fisher_post, names=["a", "b"], labels=[r"a", r"b"],
...     label="Fisher + correlated prior",
... )
>>> dk_red = "#f21901"
>>> dk_yellow = "#f2b701"
>>> line_width = 1.5
>>> plotter = getdist_plots.get_subplot_plotter(width_inch=3.6)
>>> plotter.settings.linewidth_contour = line_width
>>> plotter.settings.linewidth = line_width
>>> plotter.triangle_plot(
...     [g_like, g_post], params=["a", "b"], filled=[False, False],
...     contour_colors=[dk_red, dk_yellow],
...     contour_lws=[line_width, line_width], contour_ls=["-", "-"],
... )
>>> bool(np.isclose(logprior(theta0), 0.0))
True
(png)
Including uniform (top-hat) priors#
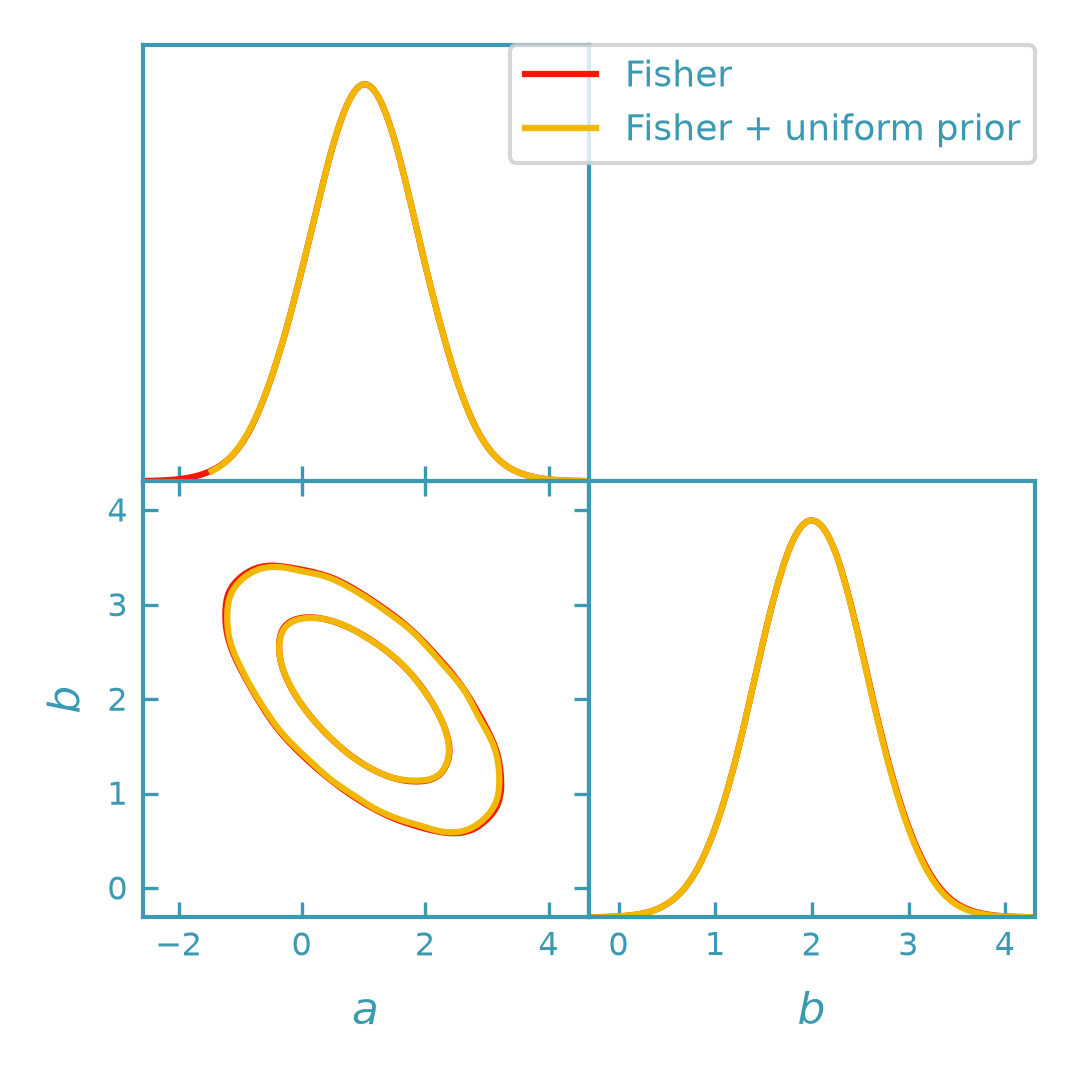
Uniform priors restrict parameters to a specified region of parameter space. Within the allowed region, the prior density is constant; outside it, the probability is zero.
Unlike Gaussian priors, hard bounds cannot generally be incorporated by adding a precision matrix to the Fisher matrix. Instead, the Fisher-Gaussian distribution must be truncated when constructing samples.
The example below uses DerivKit’s derivkit.forecasting.priors_core.prior_uniform() to impose relatively
weak bounds and compares the original Fisher contours (red) with the
truncated distribution (yellow). Unlike Gaussian priors, uniform priors
do not continuously tighten the posterior within their allowed region;
they only exclude parameter values outside their bounds.
>>> import numpy as np
>>> from getdist import MCSamples, plots as getdist_plots
>>> from derivkit import ForecastKit
>>> from derivkit.forecasting.priors_core import prior_uniform
>>> def model(theta):
...     a, b = theta
...     return np.array([a, b, a + 2.0 * b], dtype=float)
>>> theta0 = np.array([1.0, 2.0])
>>> fk = ForecastKit(function=model, theta0=theta0, cov=np.eye(3))
>>> fisher = fk.fisher()
>>> cov_fisher = np.linalg.inv(fisher)
>>> sigma = np.sqrt(np.diag(cov_fisher))
>>> bounds = [
...     (theta0[0] - 2.7 * sigma[0], theta0[0] + 4.0 * sigma[0]),
...     (theta0[1] - 4.0 * sigma[1], theta0[1] + 4.0 * sigma[1]),
... ]
>>> logprior = prior_uniform(bounds=bounds)
>>> rng = np.random.default_rng(42)
>>> draws = rng.multivariate_normal(theta0, cov_fisher, size=100_000)
>>> mask = np.array([np.isfinite(logprior(theta)) for theta in draws])
>>> truncated = draws[mask]
>>> samples_like = MCSamples(
...     samples=draws, names=["a", "b"], labels=[r"a", r"b"],
...     label="Fisher",
... )
>>> samples_prior = MCSamples(
...     samples=truncated, names=["a", "b"], labels=[r"a", r"b"],
...     ranges={"a": list(bounds[0]), "b": list(bounds[1])},
...     label="Fisher + uniform prior",
... )
>>> dk_red = "#f21901"
>>> dk_yellow = "#f2b701"
>>> line_width = 1.5
>>> plotter = getdist_plots.get_subplot_plotter(width_inch=3.6)
>>> plotter.settings.linewidth_contour = line_width
>>> plotter.settings.linewidth = line_width
>>> plotter.triangle_plot(
...     [samples_like, samples_prior], params=["a", "b"],
...     filled=[False, False], contour_colors=[dk_red, dk_yellow],
...     contour_lws=[line_width, line_width], contour_ls=["-", "-"],
... )
>>> bool(np.all((truncated >= np.array(bounds)[:, 0]) &
...             (truncated <= np.array(bounds)[:, 1])))
True
(png)
Notes and conventions#
The Fisher matrix is inverted using a pseudo-inverse to form the Gaussian covariance; regularization can be controlled via
rcond.getdist.MCSamples.loglikesstores minus the log-posterior (up to an additive constant), following GetDist conventions.Sampler bounds and priors are optional and intended for light truncation, not for defining complex posteriors.
Sampling-based Fisher contours are estimated via kernel density methods and may appear slightly irregular even for large sample sizes (e.g.
n_samples=100_000). This is expected and does not indicate an issue with the Fisher matrix itself.For strongly non-Gaussian posteriors or curved degeneracies, consider using the DALI expansion or a full sampler instead.
See also#
derivkit.forecast_kit.ForecastKitderivkit.forecast_kit.ForecastKit.fisher()derivkit.forecast_kit.ForecastKit.getdist_fisher_gaussian()derivkit.forecast_kit.ForecastKit.getdist_fisher_samples()